Loan-to-Value (LTV) Calculator
See your current LTV and the borrowing room your home equity could provide.
Explore your equity options
A bank's decision does not tell the whole story about your equity.
If you are self-employed, have credit challenges or are between roles, a mortgage specialist can help you explore alternatives to traditional bank lending.
Our equity-first approach starts with your property value, existing loans and location. This estimate shows potential borrowing room; a lender still needs to review your circumstances and confirm the terms.
Read the home-equity guidance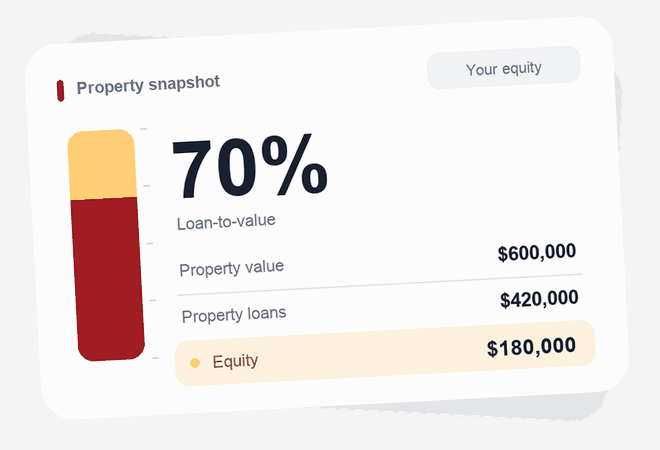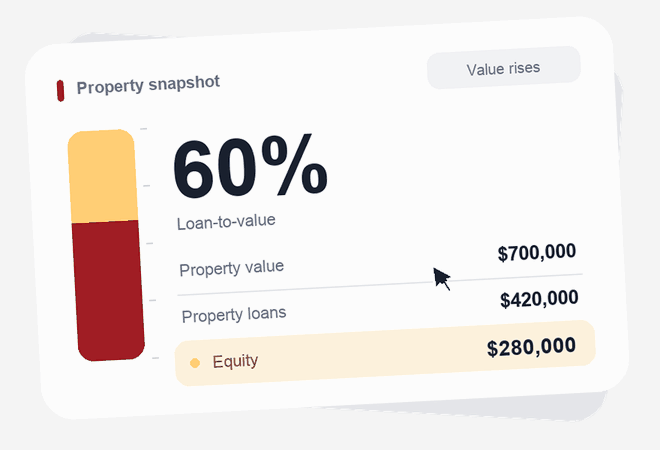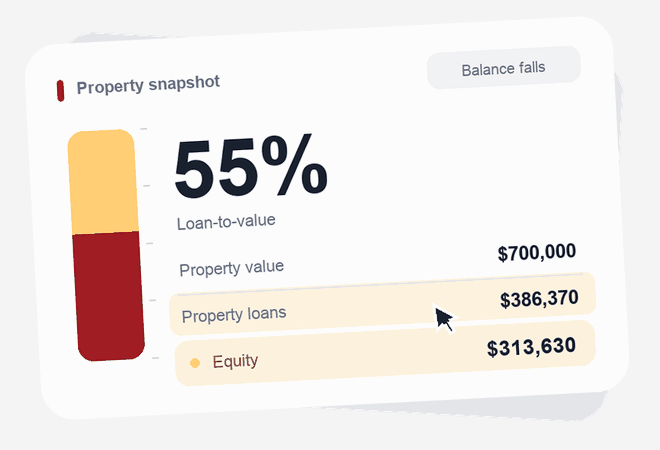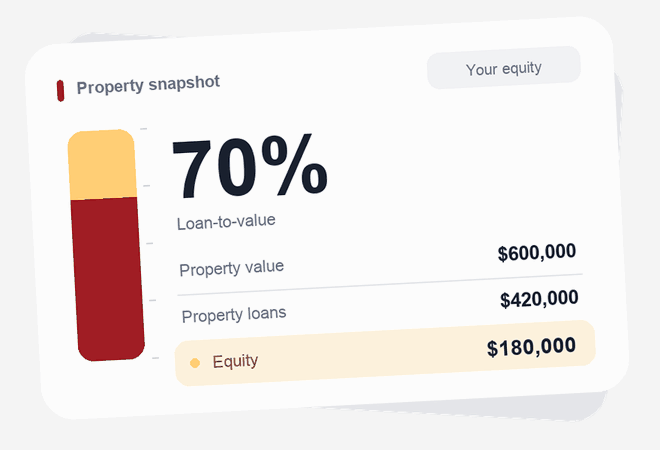
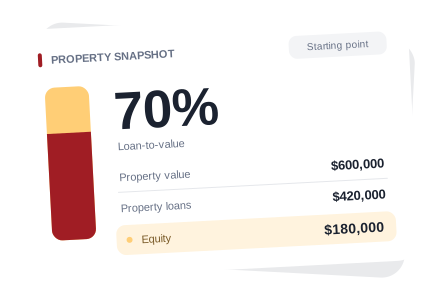
Illustrative example. Equity is not the same as borrowing room.
Keep planning
Considering a refinance?
Explore ways to use your home equity and understand the costs before choosing your next step.
Explore refinancingFAQ
Frequently Asked Questions
Understand the estimate before deciding how much equity to borrow.
What does this calculator show?
It estimates additional borrowing room using your home value, existing property loans and a selected 75% or 80% LTV limit. It also shows how much remains after the debts you want to pay off. The result is before fees and lender approval.
75% vs 80% LTV: what's the difference?
These are two planning limits. At 75%, you retain more equity; at 80%, the estimate allows more borrowing. The actual limit, rate and terms depend on the lender, property and your circumstances.
How do you calculate loan-to-value?
Divide the total loans secured against your property by its value, then multiply by 100. For example, $390,000 in property loans against a $600,000 home is 65% LTV. A lender may require an appraisal.
Who is this tool for?
Ontario homeowners exploring borrowing against their equity, including those considering refinancing, a second mortgage or private financing. It can be a starting point if you are self-employed or have credit challenges, but it does not determine eligibility.
What happens after I calculate?
Choose Request a quote to share your contact details with Mortio. A mortgage specialist will review your scenario and discuss lender options. Calculating an estimate does not submit a mortgage application.
Does a high LTV mean a higher rate?
LTV is one factor lenders consider when setting rates and terms. Credit, income, property details and the type of financing also matter. A higher borrowing estimate is a ceiling to explore, rather than a spending target.