Mortgage Broker in Mississauga
Mortgage advice for Mississauga buyers and homeowners, from condo purchases to renewals and move-up plans.
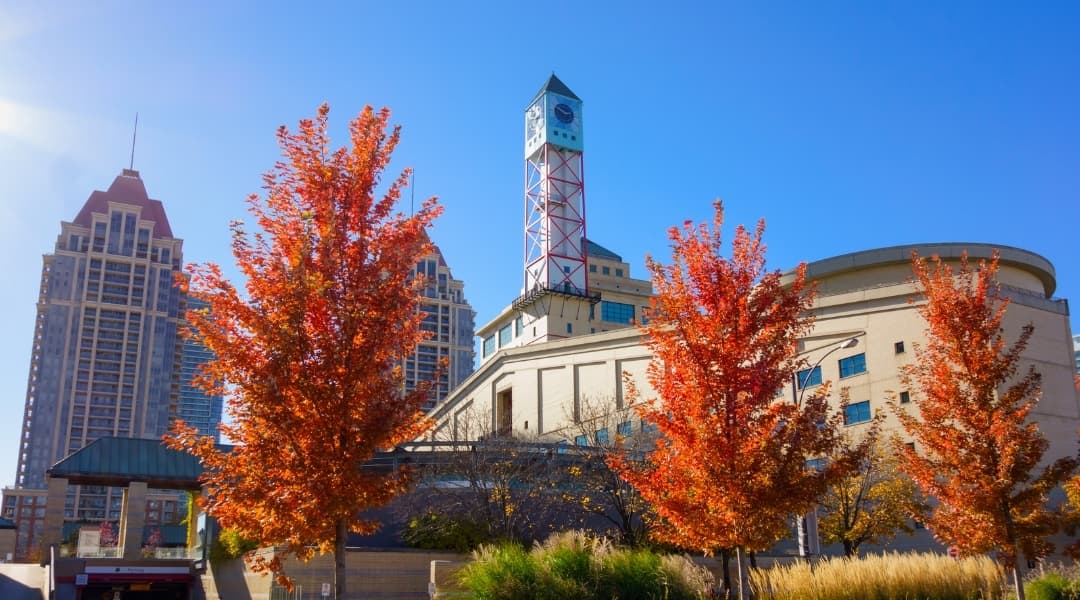
A Mississauga condo near City Centre and a freehold home in Streetsville are not the same financing file. Maintenance fees, property taxes, down payment and the lender’s view of the property all affect the true monthly cost. Before you choose a price range, make room for legal costs, land transfer tax and a payment that still works after closing.
If you are moving within Peel Region, timing can matter as much as the rate. We can compare bridge-financing needs, proceeds from your current home and the conditions attached to a new mortgage. Renewers and refinancers can also review whether staying with the current lender is actually the best fit for the next term.
August 2026 market snapshot
What homes sold for in Mississauga
435 homes sold that month
Overall average sold price
$898,510
Across all home types sold in Mississauga during August 2026.
Detached average sold price
$1,275,221
Freehold townhouse average sold price
$874,772
Condo apartment average sold price
$495,052
These are average sold prices from August 2026, not current asking prices or a valuation of any individual home. A property's price and financing depend on its condition, location and the details of your application.
Source: Toronto Regional Real Estate Board (TRREB), Market Watch, August 2026. View Market Watch archive
Plan a Mississauga mortgage payment
We started with the August 2026 average sold price. Change it to your own budget, then adjust the down payment and rate. This is a planning estimate, not a rate quote or approval.
Purchase price
$898,510
Estimated monthly payment
$3,978
What this payment includes
Mortgage principal and interest over 25 years, using the illustrative rate you select.
Budget for these separately
- Property taxes and home insurance
- Condo fees and utilities, if applicable
- Land transfer tax and closing costs
- Mortgage default insurance, if required
With less than 20% down, a mortgage insurance premium may apply. This estimate does not calculate that premium or determine mortgage eligibility.
Down payment
Illustrative interest rate
- Down payment
- $179,702
- Mortgage amount
- $718,808
Assumes a 25-year amortization. See the payment breakdown for costs this estimate excludes.
Mississauga in the 2021 Census
A longer view of the community behind today's housing market.
2021 Census of Population
Population
717,961
2021 Census
Population change
-0.5%
2016 to 2021
Occupied homes
244,575
Private dwellings occupied by usual residents
Adapted from Statistics Canada, 2021 Population and dwelling counts. This does not constitute an endorsement by Statistics Canada of this product. These are census characteristics, not current property valuations.
What the numbers mean if you are financing here
Mississauga’s monthly average includes a mix of condominium apartments, townhouses and detached homes. It is useful for context, but it will not price a particular home or tell you what a lender will approve. Choose the closest property type, then replace the sample price with the one in your own offer or budget.
Who is buying in Mississauga
Some Mississauga households are buying their first condo; others are selling one property to buy another. In either case, the deposit, down payment source and timing of the sale need to be clear before a lender can make a reliable commitment.
Lender considerations in Mississauga
For condo purchases, lenders may review the building and its status documents as well as your income. If you are selling and buying close together, ask about closing dates, bridge financing and any penalty on your current mortgage.
Mortgage help for Mississauga
Our Markham-based team helps Mississauga buyers and homeowners review purchase, renewal and refinance options by phone or online.
Land transfer tax in Mississauga
Buyers in Mississauga pay the Ontario land transfer tax only — there is no municipal land transfer tax here, unlike the City of Toronto.
Mississauga is in Peel Region and charges no municipal land transfer tax. Only the City of Toronto levies a second land transfer tax in the GTA, so an identical purchase price costs a Toronto buyer roughly twice as much in transfer tax as it costs here.
- 0.5% on the first $55,000
- 1.0% on $55,000.01 to $250,000
- 1.5% on $250,000.01 to $400,000
- 2.0% on $400,000.01 to $2,000,000
- 2.5% above $2,000,000 on one and two single-family residences
First-time buyers can claim a provincial rebate of up to $4,000.
A Mississauga condo may bring maintenance fees and status-certificate costs into the budget. If you are selling another home, account for the mortgage payout, selling expenses and deposit timing.
Neighbourhoods we finance in
Port Credit
Waterfront village pricing with a mix of century homes and new mid-rise. Older properties here often need an appraisal-led conversation about condition before a lender commits.
City Centre / Square One
The densest condo supply in the city. Strong first-time buyer territory, and the area where pre-construction appraisal gaps show up most often.
Lorne Park & Mineola
Mississauga at its most expensive. Many purchases here exceed the $1.5M insured cap, which means 20 percent down and uninsured pricing.
Erin Mills & Churchill Meadows
Family move-up market of detached and freehold townhomes. The most common profile for a purchase-plus-improvements file in the city.
Meadowvale & Streetsville
Established neighbourhoods next to the business parks, with a high share of self-employed borrowers who need income documented differently.
Malton & Cooksville
The most affordable entry points in Mississauga. Frequently multi-generational purchases where a co-signer or blended income strengthens the file.
Mississauga mortgage questions
Begin with the actual listings, not a citywide average. A condo budget needs maintenance fees and a building review; a freehold house may need more room for repairs, insurance and property taxes.
Nearby cities
Ready to see your Mississauga options?
We compare multiple lender options and explain the trade-offs in plain language. No obligation, no credit check to start.